Nigeria’s banking stocks have emerged as some of the strongest performers on the Nigerian Exchange in 2026, but business leaders say the dominance of financial institutions among the market’s most valuable companies also points to deeper challenges in the structure of the economy.
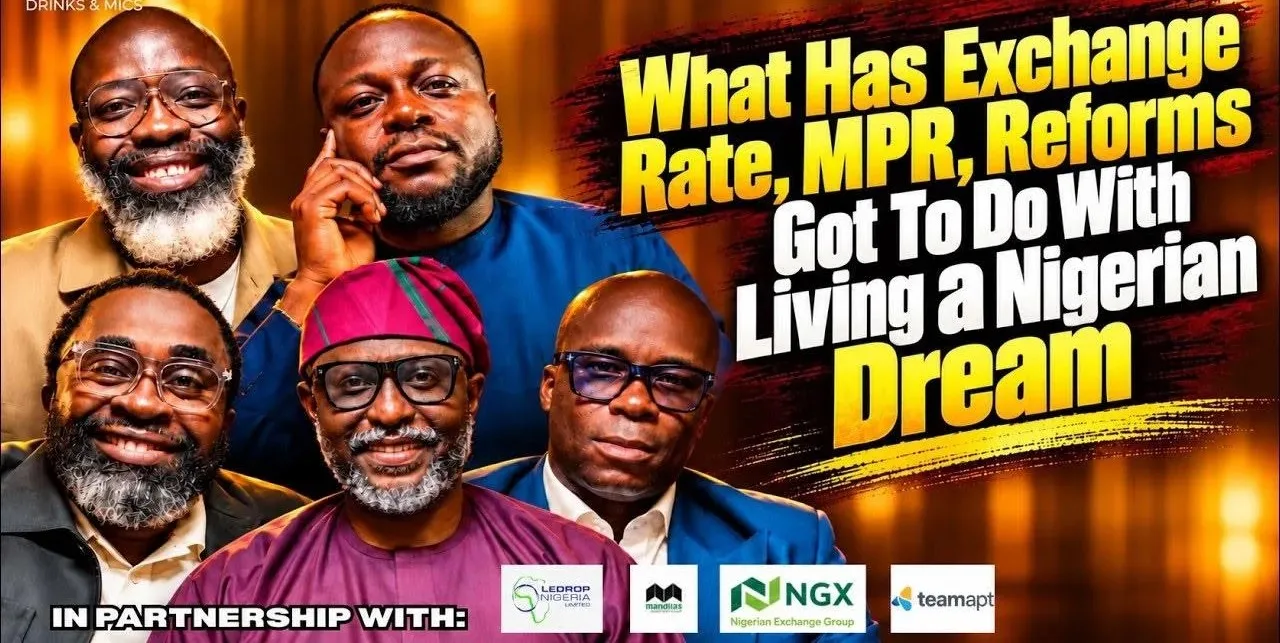
The concerns were raised by Oluwatobi Joshua Ajayi, founder and chief executive officer of Nord Automobile Limited, and Olukayode Olusanya, founder of Oak Holdings, during a recent episode of the Drinks and Mics podcast hosted by Ugodre Obi-Chukwu.
Ajayi argued that sectors such as manufacturing, agriculture and real estate should play a larger role in creating economic value and occupying leading positions on the stock market.
In his view, banks are expected to provide financing that enables businesses to expand production and investment, rather than becoming the most prominent beneficiaries of economic activity themselves.
Olusanya similarly called for changes in the way capital moves through the Nigerian economy, particularly in the way banks provide financing to businesses that require longer investment periods.
The discussion comes at a time when Nigerian banking shares have recorded a substantial rally.
Data reported by Nairametrics showed that the NGX Banking Index had gained 67.96 per cent year-to-date as of September 14, 2026, compared with a 56.35 per cent increase in the broader NGX All-Share Index.
The rise in share prices pushed the combined market capitalisation of 12 banks tracked in the analysis from approximately ₦16.44 trillion at the end of December 2025 to ₦27.61 trillion by September 14, 2026.
That represents an increase of about ₦11.17 trillion in less than nine months, with most of the increase attributed to higher share prices rather than new listings.
The performance, however, does not necessarily mean that Nigerian banks have become more highly valued than their African counterparts.
A separate analysis found that several Nigerian lenders were still trading at lower price-to-earnings or price-to-book valuations than comparable banks in markets including Kenya, South Africa, Ghana and Tanzania. Some Nigerian banks were also trading below the value of their net assets.
The strong market performance has therefore occurred alongside continued questions about how investors value the Nigerian banking sector and the sustainability of banks’ earnings.
For Ajayi, the bigger issue is the composition of Nigeria’s corporate economy. He argued that businesses involved in producing goods, developing infrastructure, farming and building productive capacity should have a stronger presence among the companies driving market value.
His position reflects a broader economic argument: a financial sector can help channel capital into the economy, but sustained growth also depends on businesses that produce goods and services, create jobs and expand productive capacity.
Olusanya focused particularly on the cost and structure of financing. He argued that the banking system remains heavily oriented towards short-term commercial transactions, making it difficult for businesses such as real estate and manufacturing that may require several years before investments generate returns.
The business leader also pointed to the banking-sector recapitalisation programme and foreign capital inflows as factors that, in his view, should create room for more affordable financing for productive businesses.
The comments come against the background of the Central Bank of Nigeria’s ongoing efforts to strengthen banks’ capital positions. The recapitalisation exercise requires affected commercial banks to meet new minimum capital requirements, with the deadline for compliance set for March 31, 2026. The CBN has said the exercise is intended to strengthen the resilience of the banking system and support economic growth.
The structure of bank financing remains an important issue for Nigerian businesses because many productive sectors require funding for equipment, factories, property, technology and expansion over extended periods.
Short-term credit can be useful for working capital and trading activities, but businesses undertaking long-term investments may require financing arrangements that better match the period over which those investments generate returns.
The debate also comes as Nigeria seeks to attract more private capital into manufacturing and other non-oil sectors while improving the country's ability to create jobs and expand domestic production.
For investors, the 2026 banking rally has demonstrated strong market confidence in listed lenders. For the wider economy, however, the more important question is whether stronger banks and higher market valuations can translate into greater financing for productive businesses.
The views expressed by Ajayi and Olusanya are their assessments of Nigeria’s economic and financial structure rather than a consensus position of the banking industry or the CBN.
Ultimately, the performance of Nigeria’s capital market will depend not only on the continued strength of financial institutions but also on whether more productive sectors can attract capital, expand operations and build companies capable of competing for a larger share of market value.
Reporting by TalkNaijaMedia
Reader Comments (0)
No comments yet. Be the first to share your perspective on this report.